The HVAR Elementwise Lasso model is an extension of the VARX Lasso model (see VARX Lasso) where a special hierarchical penalty is used. This penalty offers not only regularization to avoid over-fitting in terms of shrinking parameters towards zero, but also automatic selection of maximum lag order.
The HVAR Elementwise Lasso model allows selection of lag order per variable and indicator per equation. Different variables in a VAR system may exhibit distinct temporal dependencies. Allowing variable-specific lag orders accommodates variations in the speed at which different variables respond to past values of themselves and other variables. This enhances the model's ability to capture the unique dynamics of each variable. This model is more flexible than HVAR Componentwise Lasso, which may be beneficial when there is a large number of observations available, but also increases the risk of over-fitting the model to the data if the observation count is low.
Mathematically, the penalty structure is defined for k variables and a maximum of p lags as
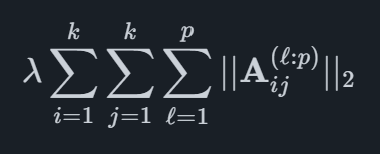
where each term in the inner sum contains the p−l+1 matrices corresponding to lags l,...,p.