Exponential smoothing is a simple model which describes the current value as a weighted average of the two previous values. As such, only a single parameter αα is needed. Denoting the variable value at time t as Yt we can define a new smoothed series St as
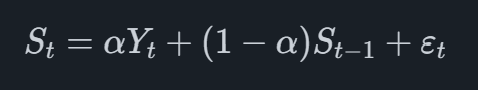
where εt is the error at time tt.
For seasonal data, it is also possible to have an ETS model which
There are numerous variations of the ETS model, varying in three different ways. The error term εt and/or the additive terms αYt−1 and (1−α)Yt−2 can enter the model as multiplicative terms as well. Finally, for seasonal data it is possible to add a seasonal term, i.e. for monthly data (1−αs)Yt−12
These variations are selected based on Akaike's Information Criterion (AIC), which selects the most simple model while still maintaining a good fit to the data.