New30 Oct 2026When the Forecast Becomes the Target: How to Keep Your Numbers Honest
Indicio

Home / Model library / Multivariate, group Lasso

Model library · Multivariate, group Lasso

VAR Lag weighted Lasso

Consists of a Lasso penalty that increases geometrically with lag. This means that shorter lags are prioritized in these models, compared to the set up in other VAR models.

The VAR Weighted Lag Lasso model is an extension of the VARX Lasso model which increases geometrically as the lag order increases. This has the effect of penalizing higher lags more than lower.

The weighted lag lasso penalty can be written as
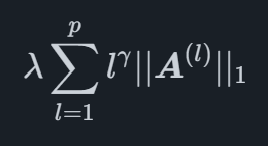
where γ is a second hyperparameter which determines the shape of the increased penalty for the higher lags. The intuition behind the penalty is that for a series which is affected more by recent developments than developments further back, the coefficients further back should be penalized more heavily.

You don't have to pick the model

Indicio tests this model on your history next to 80+ others, at every horizon, and keeps the ones that forecast best. With leading indicators chosen for you from over 400 million series, and every number explained.

Book a demo