The Autoregressive Distributed Lag (ARDL) model is similar to the univariate ARIMA model but with the option to use it for multiple variables simultaneously.
In the article about the ARIMA model a simple autoregressive model with p lags was written as
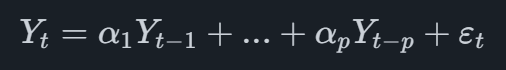
where αi is the coefficient for lag i and εt is the error term.
Such a model can also employ one or more exogenous variables X, which enters the model just as the lags of the main variable. This can be written as
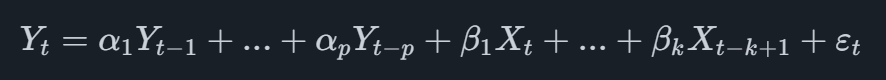
where we have a single exogenous variable with k lags. These lags are what is said to be the distributed lags of the model, giving it its name.
We can now see that for a forecast of three steps ahead, the exogenous variables must be know up until T+3, which they usually are not. The ARDL model works by creating univariate ARIMA models for each indicator to produce the forecasted values needed. These are then lagged and enters the main model, which in turn is also an ARIMA model which allows for bot AR and MA terms as well as handling non-stationary data.
How does Indicio fit an ARDL model
Selecting the AR, MA and differencing order for each ARIMA model within an ARDL model poses a challenge as many options exists. For the ARIMA models of each indicator variable, the same methods as in the univariate ARIMA model are employed.
For the selection of the lag order of the indicators into the main model and also the AR order of it, a joint evaluation is made where a large number of options are evaluated and a selection is made based on the best AIC value. As mentioned in some other articles, AIC penalizes adding more parameters if they do not improve model fit enough.